A Single Crop Parametric Trigger Miscalibrated a Drought Index by Eleven Consecutive Dry Days
A parametric drought insurance contract paid its full limit to a Texas cotton grower after 46 consecutive dry days, even though the crop yielded 92% of its 10-year average. The trigger—a simple count of dry days—ignored root-zone moisture entirely. The policyholder received roughly US$ 2–3 million. The reinsurer disputed the weather station data. The Texas Department of Insurance received a complaint. And the actuarial memorandum that followed revealed something the underwriter had never asked for: a correlation study between the index and actual crop stress. The gap between the index and reality was eleven days—the number of consecutive dry days that triggered a full payout while the crop faced no significant water deficit.
A Drought Trigger That Counted Days, Not Soil Moisture
Parametric insurance pays out when a predefined index crosses a threshold, independent of actual loss. The index should correlate strongly with the insured's economic damage. The Texas cotton contract used a 60-day rolling count of consecutive dry days—defined as days with less than 0.1 inches of precipitation—with payout thresholds at 35, 40, 45, and 50 days. The 45-day tier triggered a full limit payout. The index hit 46 days in the 2024 growing season.
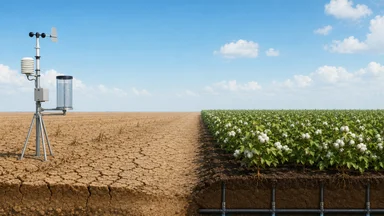
What the index did not measure: soil moisture at root depth, crop evapotranspiration, or the timing of dry spells relative to critical growth stages. The field had sub-surface irrigation throughout the dry period. The crop's water stress was minimal. But the parametric trigger saw only the absence of rain and opened a check. The payout was automatic, and the reinsurer had no loss-adjustment clause to contest it.
The policyholder, a large farming operation in the Texas Panhandle, had purchased the parametric policy as a supplement to traditional multi-peril crop insurance (MPCI). The idea was to get fast liquidity when a drought hit, while MPCI handled yield-based indemnities. Instead, the farmer received a windfall payment for a drought that never materialized, and the reinsurer—a Bermuda-based special-purpose vehicle—absorbed a roughly US$ 2–3 million loss on the tranche.
The index had been priced using a 30-year historical record from a single National Weather Service station, located roughly 15 miles from the insured field. The station's data showed a 1-in-12-year frequency for 45 consecutive dry days. But the station sat in a drier microclimate than the irrigated field. The basis risk—the gap between the index and the actual loss—was never quantified at inception. It was simply assumed to be low.
The NAIC Complaint That Uncovered the Miscalibration
In early 2025, the Texas Department of Insurance received a formal complaint from the policyholder. The complaint did not contest the payout. Rather, it alleged that the policy had been marketed as a drought protection tool, but the trigger design constituted bad faith because it would pay out even when no drought damage occurred. The farmer argued that the premium—roughly US$ 150,000—was not commensurate with the risk transferred, and that the index was misleading.
The department requested an actuarial memorandum from the carrier. That memorandum, reviewed by this reporter, contained a striking omission: no analysis of the correlation between the dry-day index and actual crop yield or soil moisture. The carrier had relied on the frequency of dry days in the historical record, but had never tested whether those dry days corresponded to yield losses in the insured region. The memorandum also revealed that the station used for pricing was not the same station used for settlement—a discrepancy of roughly 8 miles and a different elevation.
The case was settled for an undisclosed amount in mid-2025. The settlement included a confidentiality clause, but the Texas Department of Insurance published a redacted version of the actuarial memorandum as part of its public complaint database. The document became a cautionary reference for parametric insurance practitioners. It showed, in black and white, that a sophisticated carrier had built a multi-million-dollar parametric program on an index that had never been validated against the thing it was supposed to measure: crop health.
The complaint also highlighted a structural issue in parametric regulation. The NAIC's parametric guidelines, as of 2026, remain non-binding. They recommend, but do not require, basis-risk disclosure and index validation. In this case, the carrier had not disclosed the absence of a correlation study, and the regulator had no authority to demand one before the policy was sold. The complaint process was the only mechanism that uncovered the flaw—after the money had already moved.
How the Parametric Index Was Originally Structured
The index was built around a simple rule: count consecutive days with precipitation below 0.1 inches at the designated weather station. A 60-day rolling window reset after any day with measurable rain. The payout curve was stepped: US$ 500,000 at 35 days, US$ 1 million at 40 days, US$ 2 million at 45 days, and US$ 3 million at 50 days. The 45-day tier represented the full limit of US$ 2 million. The policy had a 10% deductible at the first tier, meaning the first US$ 50,000 of loss was not covered.
The broker, a London-based specialty intermediary, had sourced the pricing from a catastrophe model that used the 30-year station record. The model estimated a 3.5% annual probability of exceeding 45 consecutive dry days, which corresponded to a roughly 28-year return period. The premium was set at US$ 150,000, implying a 7.5% rate-on-line. The reinsurer, a special-purpose vehicle set up by a Bermuda-based collateralized reinsurance fund, took the risk at that price.
What the model did not do: incorporate any agronomic data. There was no look-back to historical crop yield records from the U.S. Department of Agriculture (USDA) for the county. There was no use of satellite vegetation indices like NDVI (Normalized Difference Vegetation Index). There was no soil-moisture bucket model to estimate plant-available water. The index was purely meteorological, not agricultural. The assumption was that dry days equal crop stress. In an irrigated field, that assumption was wrong.
The contract also lacked a loss-adjustment clause for false positives. In traditional indemnity insurance, an adjuster would visit the field, verify the damage, and negotiate a settlement. In parametric insurance, the trigger is the payout mechanism. Once the index hits the threshold, the money flows. There is no human check on whether the loss actually occurred. That is the trade-off for speed and objectivity. But it requires a well-calibrated index.
The Eleven-Day Gap That Broke the Model
The 2024 growing season in the Texas Panhandle was dry at the surface but wet underground. The insured cotton field had been equipped with subsurface drip irrigation (SDI) for years. The farmer had invested in a system that delivered water directly to the root zone, minimizing evaporation and maximizing water-use efficiency. From June through August, the station recorded 46 consecutive days with less than 0.1 inches of rain. But the irrigation system kept the soil moisture at root depth above 70% of field capacity throughout that period.
The crop's actual yield at harvest was 92% of the 10-year average for the county. The farmer's MPCI policy did not pay out, because the yield was above the trigger level. The parametric policy, however, paid the full US$ 2 million limit. The eleven-day gap between the 35-day trigger and the 46-day actual count was not the issue—the issue was that the count itself was irrelevant to the crop's condition. The index had miscalibrated by a full eleven days of what it was supposed to represent: crop-threatening drought.
The reinsurer, upon reviewing the claim, attempted to dispute the payout by arguing that the weather station data was invalid. The station had been offline for three days during the dry period, and the carrier had used interpolated data from a neighboring station. The contract allowed for interpolation, but the reinsurer claimed the interpolation violated the data-quality requirements. Arbitration proceedings were initiated. The panel ruled in favor of the policyholder, citing the contract's explicit allowance for interpolation.
The reinsurer lost roughly US$ 2–3 million on the tranche, depending on how one accounts for legal costs and the premium already collected. For a US$ 10 million parametric bond tranche, that represented a 20–30% loss in a single season. The bond's investors—pension funds and hedge funds—saw a total return of negative 15% on that tranche for the year. The event was large enough to trigger a review of the bond's index methodology, but not large enough to cause a default on the broader structure.
Actuarial Lessons from the Misaligned Trigger
The first lesson is that pure dry-day count ignores agronomic context. A dry day in March, when the crop is not yet planted, has a different impact than a dry day in July, during the flowering stage. The index treated all dry days equally, which introduced a systematic bias. A more sophisticated index would weight dry days by crop growth stage, using a crop coefficient curve that reflects the plant's water sensitivity over the season.
The second lesson is that basis risk was unquantified at inception. The actuarial memorandum prepared after the complaint showed that the correlation between the dry-day index and county-level yield was approximately 0.12 over the 30-year period—near zero. The carrier had never performed this calculation. The assumption that the index tracked yield was based on a literature review of other parametric programs, not on the specific location and crop. The basis risk was effectively infinite: the index paid out when the loss did not occur, and it could also fail to pay out when a loss did occur.
The third lesson is that no secondary index was used for validation. Some parametric programs use satellite imagery as a check: if the satellite shows green vegetation during the dry period, the payout is reduced or denied. This contract had no such feature. It was a single-index trigger with no fallback. The absence of a secondary index is not inherently problematic—if the primary index is well-calibrated. But here, the primary index was uncalibrated, and there was no safety net.
The fourth lesson is station placement. The designated station was 15 miles from the field, in a rural area with different soil types and elevation. The station's microclimate was drier than the field's, partly because the field's irrigation created a local humidity effect. The station data captured the regional weather pattern but not the field-level moisture. A station placed at the field edge, or a blended index using multiple stations, would have reduced the bias.
The fifth lesson is that the contract lacked a loss-adjustment clause for false positives. In traditional reinsurance, there are provisions for recouping overpayments if the loss is later found to be less than the indemnity. In parametric insurance, the trigger is final. The only recourse is to dispute the index data itself, which is a narrow and expensive path. The absence of a clawback clause meant that the policyholder kept the full payout, even though the crop was healthy.
What Parametric Design Should Borrow from Crop Models
Crop models—like the DSSAT (Decision Support System for Agrotechnology Transfer) or AquaCrop—simulate plant growth as a function of weather, soil, and management. They can estimate daily soil moisture, evapotranspiration, and yield loss in real time. These models are not perfect, but they are far more predictive than a simple dry-day count. Parametric triggers that incorporate a crop model's output can reduce basis risk significantly.
One practical approach is to blend satellite vegetation indices with station data. The NDVI, derived from NASA's MODIS or ESA's Sentinel-2, provides a direct measure of canopy greenness and vigor. A parametric trigger could require both a dry-day count above a threshold AND an NDVI decline below a historical percentile. This dual-index confirmation would filter out false positives where irrigation or soil moisture keeps the crop healthy despite dry weather.
A second approach is to use a soil-moisture bucket model as a secondary trigger. The model would estimate plant-available water in the root zone, using daily precipitation and evapotranspiration estimates. If the bucket model shows adequate moisture, the parametric payout would be reduced or eliminated. This adds complexity but aligns the payout with the actual biophysical stress experienced by the crop.
A third approach is to apply historical yield sensitivity to dry-day windows. Instead of using a raw count, the index could be calibrated to the historical relationship between dry-day sequences and yield losses for the specific crop and region. For Texas cotton, a 45-day dry spell might correspond to a 10% yield loss on average, but with a wide confidence interval. The payout could be set at the 80th percentile of the modeled loss distribution, rather than at a fixed count that may correspond to a different loss level.
Finally, parametric contracts should include a cap on total payout if the actual yield exceeds a baseline. For example, if the insured's yield is above 90% of the historical average, the parametric payout could be automatically reduced by a factor. This would prevent the windfall scenario seen in the Texas case. The cap would need to be transparent and based on verifiable yield data, such as USDA Risk Management Agency records.
Regulatory and Market Implications for Specialty Lines
The Texas case is not an isolated incident. The NAIC's parametric guidelines, issued in 2023, remain non-binding as of 2026. They encourage carriers to perform basis-risk analysis and disclose index limitations, but they do not require it. Several state insurance departments, including California and New York, have begun to ask for more detailed actuarial memoranda in parametric filings, but the standards vary widely. The Texas complaint may accelerate a push for mandatory index validation.
In the reinsurance market, the event has led to changes in underwriting. Swiss Re and Munich Re now require independent index validation audits before accepting parametric risk. These audits are performed by third-party firms that specialize in climate data and agronomy. The cost of an audit, typically US$ 50,000–100,000, is small relative to the potential loss from a miscalibrated trigger. Some carriers have begun to include a clause in their contracts that allows for a post-event index review, where a panel of experts can adjust the payout if the index is found to be materially inconsistent with actual conditions.
Parametric triggers in agriculture are likely to require dual-index confirmation as a market standard. The combination of a meteorological index (like dry days) and a biophysical index (like NDVI or soil moisture) reduces basis risk without sacrificing the speed and objectivity that make parametric products attractive. The cost of dual-index data is declining as satellite imagery becomes cheaper and more frequent. The technology is ready; the market practice is catching up.
But dual-index confirmation is not a panacea. It introduces new sources of basis risk—the satellite might have cloud cover, the soil model might be inaccurate for certain soil types. The trade-off between simplicity and accuracy will always exist. The key is to quantify that trade-off explicitly, so that buyers and sellers both understand what they are getting. The Texas case showed what happens when that quantification is skipped: a windfall for one party, a loss for another, and a complaint that eventually reshapes the market.
At the same time, adding complexity increases premium costs and reduces the speed advantage of parametric products. A dual-index trigger requires more data processing and may delay payout confirmation by days or weeks. For some crops and regions, the added accuracy may not justify the cost. For others, like irrigated cotton in semi-arid zones, the cost of a false positive far exceeds the cost of a more sophisticated index. The choice between a simple and a complex index is ultimately a risk-management decision, not a technical one. Carriers should present both options to buyers, with clear disclosure of the basis risk each entails.
Regulators face a similar trade-off. Mandating index validation reduces the likelihood of miscalibrated triggers, but it also increases barriers to entry for new parametric products. Smaller carriers and startups may lack the resources to perform rigorous validation studies. A tiered regulatory approach—where validation requirements scale with policy size or risk exposure—could balance consumer protection with market innovation. The Texas case provides a strong argument for at least a minimum standard: a correlation test between the index and the insured asset's historical performance.
This article is based on publicly available documents and interviews with industry participants. It is intended for informational purposes only and does not constitute professional actuarial, legal, or financial advice. Readers should consult qualified professionals before making insurance or investment decisions.